Paying overseas with USDT: count the cost behind the convenienceWhat paying with stablecoin and Binance Pay involves, and who it fits

What this route buys you is the end of the decline-and-retry ordeal: the money skips the cross-border risk control at your bank and the card network entirely. What it costs you is three things you now have to watch yourself: whether the platform is legitimate, whether the counterparty is trustworthy, and whether this is allowed where you live. Who it fits: people whose card keeps getting declined, paying a clearly crypto-friendly, reputable merchant, willing to learn the flow once themselves. Who it doesn't: anyone who just wants an easy button and won't read the rules, anyone being talked into paying a fee first to unlock something, or anyone in a region with clear limits on crypto who isn't sure where they stand. For them the risk far outweighs the hassle it saves. This site makes no compliance call for any country; whether it is legal where you are is for you to judge by your local law. From 30 September 2026, visitors in Japan can also pay with Binance Pay at PayPay shops; who qualifies, how it works and what to do if it fails are in the PayPay in Japan section.
What's in this guide (open the outline)
- How to pay with USDT, from buying the coin to paying
- Where it saves: why it sidesteps a decline
- The three places your money most often leaks
- Choosing between chains, and sending to the wrong one
- The three risks on the back side, skip none of them
- Who it fits and who it doesn't: sort yourself in
- Three real scenarios: should you take this route?
- Can you pay with Binance Pay at PayPay in Japan? Who qualifies and how to pay
- A tickable list before you register and use it
- Where you most often lose money or get scammed
- When you must stop immediately
- Send an amount small enough not to hurt, and finish the flow
- A few questions people ask
How to pay with USDT, from buying the coin to paying
"Paying for overseas services with USDT" sounds like a fog to a lot of people. Take it apart and it is really two steps: first you get hold of some USDT, then you spend it. USDT is a "stablecoin", designed to track one US dollar so it works as a relatively steady unit inside the crypto world. It isn't something you trade for ups and downs; it is meant for moving money and paying.
Step one, get hold of USDT. Where it's legal where you live, most people buy it on a crypto exchange with local currency, a bank card or a third-party method. This usually means registering and finishing identity verification before you can deposit and trade. The USDT then sits in the wallet on your exchange account.
Step two, spend the USDT. There are two common routes:
- Pay a crypto-friendly merchant directly with Binance Pay. Binance Pay is a payment feature built into the exchange. If the service you want (some cloud services, SaaS, certain overseas merchants) clearly accepts it, you can pay that service fee straight from your wallet's USDT, like scanning a code or sending a transfer, with no bank card in the middle.
- Top up a "crypto virtual card". If the merchant doesn't take crypto but you hold a virtual card that accepts USDT top-ups, you move the USDT onto the card, turn it into card balance, then pay the site with that card. The final step is still a card swipe; only the source of the money has changed. How to pick a card like that is in the related reading below.
So the whole line is: local currency → buy USDT on an exchange → (pay the merchant with Binance Pay | or top up a virtual card and swipe it). It sounds like a fair few steps, but each has a clear thing to check against; it isn't a black box. Once you can see this line, the rest of the guide will land.
Buying stablecoins such as USDT and using them to move money across borders is regulated very differently from one country to the next, and some places restrict or ban it outright. This guide is written for readers where doing so is permitted. Check the rules where you live and follow local law before you act.
Where it saves: why it sidesteps a decline
If you found this route because your card keeps getting declined on overseas sites, what it saves you is very concrete:
- It sidesteps the issuer's cross-border risk control. A lot of declines happen because your bank treats "an online transaction from an unfamiliar country" as suspicious. The USDT route never touches the card rail, so that risk control has nothing to catch.
- Cross-border flow is smoother. Paying a merchant registered abroad, the card rail often jams on currency, region or merchant category. A stablecoin transfer doesn't care about borders, and confirmation tends to be quicker than international card clearing.
- It avoids "this merchant only takes cards from certain countries". Some sites won't accept a card issued in your region. If the site takes Binance Pay or crypto, you have a way to pay that doesn't depend on where your card was issued.
But one caveat is worth repeating: what it saves is the hassle on the "rail", not necessarily the overall cost. Buying USDT has a fee, transfers carry a network fee (often called gas), and topping up a virtual card may add another. On Binance on 28 September 2026 that meant 0.1% to buy on the spot market (0.075% with BNB) and a flat withdrawal fee from 0.01 USDT on BNB Smart Chain to 1.5 USDT on Tron; the full list is in the USDT fee table. Whether it genuinely saves money is something you add up against your old method, not assume.
The three places your money most often leaks when buying USDT
The first time I took this route, my head was fixed on one thing: "the fee". I assumed the rate printed on the exchange page was the whole cost. Only after running it through once did I realise that what actually makes "the USDT I ended up with is a bit less than I expected" is usually not that clearly-labelled fee, but a few spots tucked inside the flow that the page doesn't always spell out in big letters. Lay them out and you won't end up counting only half the cost.
One: the gap between the buy price and the "reference" price
The price you see when buying USDT isn't necessarily the price you finally settle at. If you use a "quick buy" convenience route, the platform usually folds its service into the quote, so there's a small gap between what you pay and the mid-market rate; if you use the order book (placing a limit buy), your fill depends on the bids and asks at that moment. That gap isn't a scam, it is one of the costs of the route. It isn't fixed, and it floats with the market and the route you pick, so before you confirm, glance at the two numbers that matter (how much local currency you pay and how much USDT you receive), not just the percentage fee. The gap moves with the market, so the two numbers on your own confirmation screen are the ones that count.
Two: the deposit-rail fee
What many people overlook: moving money from your bank card or local payment into the exchange account, the "deposit" itself, sometimes carries a cost too. Different deposit methods (bank transfer, third-party payment, card rail) differ in fee and speed; some are free but slow, some are fast but take a cut. This fee is separate from the trading fee that comes later, and it's easy to miss. On your first run, look at the deduction on each of the two steps, deposit then buy, separately, so you know exactly which step the money went missing at.
Three: the network fee (gas) when you move the USDT out
If after buying USDT you don't keep it on the exchange to pay directly with Binance Pay, but instead "withdraw" it somewhere else (topping up a virtual card, sending it to another wallet), that step generates a network fee, the gas people talk about. This isn't charged by the exchange but paid to the blockchain network, and how high it runs depends mostly on which chain you pick, which is exactly what the next section is about. Pick the right chain and this fee can be tiny; pick the wrong one and gas alone can eat an amount that no longer makes the route worth it.
Put the three together and one thing becomes clear: "USDT saves money" only holds once you've added the buy-price gap, the deposit fee and the network fee into the sum. Any claim that reports just one of them and calls it "cheap" is an unfinished tally. Add the three up on a real amount before you decide; the USDT top-up cost estimator does the sum.
Choosing between chains and networks, and what happens if you send to the wrong one
This is the most technical step in the whole flow, and the one where real money most easily disappears, so it deserves its own section. USDT doesn't live on a single chain; it is issued on several different blockchain networks at once, commonly TRC20 (the Tron network), ERC20 (the Ethereum network) and others. The same USDT running on a different network differs in transfer speed, network fee, and whether the other side can even receive it. This is where beginners trip up most.
The chain is a protocol-level matter; a few facts you can state plainly
The points below hold on any exchange. The fees quoted are Binance's on one day, as an example of how far apart networks can be:
- TRC20 (the Tron network) confirms in seconds and is widely accepted by card providers and merchants, which made it the habit for moving USDT. It is no longer the cheap one to send from an exchange, though: on 28 September 2026 Binance charged 1.5 USDT per TRC20 withdrawal, against 0.3 on Ethereum and 0.01 on BNB Smart Chain.
- ERC20 (the Ethereum network) has a floating on-chain cost (gas) that rises when Ethereum is busy. An exchange smooths that into a fixed withdrawal fee, which is why Binance's ERC20 fee can sit below its TRC20 fee; sending from your own wallet, you pay the live gas instead. Its upside is the widest acceptance.
- The crucial one: the sender and the receiver must use the same network. Before you top up a virtual card or send to an address, check which chain's address the other side asks for, then withdraw on the matching network.
What sending to the wrong network does: the most expensive slip on this route
Suppose the other side gives you a TRC20 address but you pick the ERC20 network when withdrawing (or the reverse). The likely result is: the coins neither reach the other side nor come back to you easily. Because the address and network don't match, the coins land somewhere "no one can normally move them from". A crypto transfer isn't like a bank transfer you can request to reverse; it has no such mechanism, and once sent it basically can't be chased back. This isn't scaremongering; it is a real and fairly frequent kind of loss on this route.
One: confirm which chain the other side wants, then pick the network. Don't go by feel, and don't assume "it's all USDT anyway". Two: always test small the first time. Send an amount so tiny that losing it wouldn't sting, confirm they really received it, then send the normal amount. Three: not one character of the address wrong, not one network chosen wrong. Get either one wrong and the coins can be stuck for good. Better to go slow and check three times than to rush.
If it has already happened, find the transaction ID (TxID) in your withdrawal history first. If the coins went to an address on an exchange, send that TxID to the exchange's support: some run a recovery process for deposits made on the wrong network, and Binance's version, Self-Service Recovery, takes the TxID and reviews each request, for a fee that varies. If they went to your own wallet on an EVM network (Ethereum, BNB Smart Chain, Polygon and Arbitrum share one address format), add the other network in the same wallet and the coins often show up there. Anyone who contacts you offering to recover them for a fee paid upfront is the next scam.
In the end, choosing a chain isn't about studying blockchain theory; it's about building one habit: before withdrawing, check the "network" and the "address" character by character against what the receiver asked for. That habit spares you the most expensive kind of mistake on this route.
The three risks on the back side, skip none of them
This is the section to read most carefully. The "saving" above is real, but if you don't reckon with the three things below, what you save can fall far short of what you stand to lose. I'll lay them out honestly and won't soften them for you.
Risk one: whether the platform is legitimate
Whether the platform where you buy USDT and use Binance Pay is legitimate and lawfully operating in your region is the first gate. The market holds both large, regulated exchanges and copycat or impostor sites waving a low-fee flag. Getting the platform wrong, for example following a look-alike link sent in a private message or an ad, can send the money you deposit somewhere it never comes back from. So sign up and log in through a trusted entry point, don't follow links strangers send you, and confirm the platform offers service in your region. That step cannot be skipped.
Risk two: the counterparty
When you don't buy on the exchange but from "some person" (an off-exchange, private transfer), or pay an unfamiliar merchant with Binance Pay, the counterparty becomes the risk. A crypto transfer has a hard edge: once it's sent it basically can't be pulled back, with no bank-style reverse or chargeback. If they take the money and ship nothing, hand you a dead address, or you've walked into a scam dressed up as a merchant, it is hard to recover. The more unfamiliar the counterparty and the more private the deal, the higher this risk.
Risk three: local rules
Rules on holding, buying, selling and using crypto assets vary a great deal by region; some are relaxed, some have clear limits, some require you to declare it. Whether it is allowed where you are, whether you owe tax, whether there is a cap, only you can judge by your local law. This is an education site explaining the general mechanics; it makes no compliance call for any country. If you aren't sure, look it up and ask first, then decide whether to act.
Don't treat them as "pick one". A single transaction can hit all three at once: on a platform that isn't legitimate, from an unfamiliar counterparty, doing something your region doesn't allow. When the three stack, the chance of trouble doesn't add up, it multiplies. If any one of them leaves you uneasy, don't go further.
Who it fits and who it doesn't: sort yourself in
Put the saving and the risk side by side and it becomes clear who this route suits. Don't jump on it because it "sounds advanced", and don't reject it because it "sounds scary". Sort yourself against the two columns.
- Fits reasonably well: your card really does keep getting declined, what you're paying is a reputable merchant that clearly accepts Binance Pay or crypto, you're willing to learn the buy, transfer and top-up flow yourself, your region has no clear ban on crypto, and you understand the relevant tax and reporting expectations.
- Doesn't fit well: anyone who only wants the "easy button" and won't read the rules; anyone being egged on to "pay a fee first to activate or unlock it" (usually a scam, see below); anyone in a region with clear limits on crypto, or who doesn't know where they stand; and anyone just wanting to "bet on the swings" (here USDT is a payment tool, not a way to chase a price gap).
If you find yourself leaning toward the "doesn't fit" column, then rather than forcing this route, it is often steadier to go back and see whether a virtual card or a gift card solves your payment problem instead.
Three real scenarios: should you take this route?
Talking abstractly about "who it fits" is easy to forget the moment you hear it. Better to pick three scenarios I've genuinely seen, and genuinely agonised over, and weigh them one by one. You'll likely find your own reflection in one of them.
Scenario one: subscribing to an overseas SaaS or cloud service that clearly accepts crypto
This is the smoothest case for the route. What you're paying is a legitimate company whose own checkout page lists "crypto / Binance Pay accepted", not something a middleman relayed to you. Here, paying directly with USDT really does sidestep the card that keeps getting declined. The things to watch are still the same few: confirm it's the merchant's official page accepting crypto rather than an impostor, don't follow exchange links strangers send you, and run the smallest amount through first. In this scenario, "the stablecoin is a payment tool" holds in its purest form: you aren't investing, you've just swapped one payment method for another.
Scenario two: your card keeps getting declined and you want to "route around it" for an ordinary site that doesn't take crypto
This one needs an extra layer of thought. The target site itself doesn't take crypto, and you've heard "you can move USDT onto a virtual card and swipe that". The route works technically, but it has a whole extra leg over scenario one: you first need a trustworthy virtual card, then move USDT onto it, then pay with the card. Each extra leg adds a fee and a risk point (is the card seller reliable, does the top-up carry an extra charge, will the card get caught by that site's prepaid-card blocklist). Before taking it, read the piece on funding a virtual card with crypto carefully and add up the chain and the fees; don't assume. Often, first working out "why the card is declined" is simpler than routing all the way around.
Scenario three: someone comes to "teach" you to pay with USDT and offers to do it for you
I'll say this one plainly: whenever someone approaches you unprompted, eagerly "teaching" or "helping" you pay with USDT, especially if they want you to transfer a sum first or ask you for account details, you should almost always stop. Real payment doesn't need a stranger hand-holding you through moving coins. You should, and can, learn this route yourself, but the thing you learn from is the public flow and rules, not some "kind person" in your DMs. This scenario isn't a "should I take it" question; it belongs straight in the "when you must stop" section below.
Can you pay with Binance Pay at PayPay in Japan? Who qualifies and how to pay
Yes, but only if you are a visitor physically in Japan. Binance launched it on 30 September 2026: Binance Pay connects to Japan’s PayPay through the HIVEX network, so at in-person shops showing the PayPay sign you can pay straight from the crypto in your Binance account. It is converted to yen at the live rate, and the shop receives yen. You don’t need yen in the account; USDT, USDC, BTC, ETH, BNB and over 100 other coins work. Binance’s help page lists three conditions that all have to hold:
- you are in Japan, on a Japanese IP address;
- your Binance.com account has completed identity verification;
- you are on the latest version of the Binance app.
Residents of Japan can’t use it: Binance’s announcement says the feature is only visible and available to tourists visiting Japan. If you are in Japan with the app updated and still see no PayPay icon on the Pay page, one of the three conditions is probably not met (an inference from Binance’s list). Check your verification status first, then make sure your phone isn’t on a VPN set to another country.
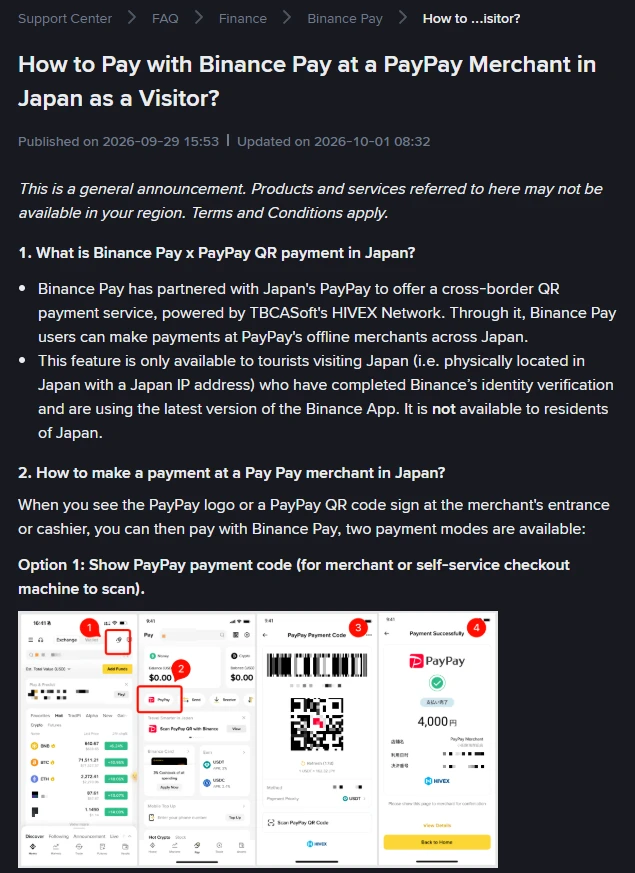
How to pay at a PayPay shop: show your code or scan theirs
- Show your payment code (for the cashier or a self-checkout to scan): on the Binance app home screen tap Pay, then PayPay, check the exchange rate, payment method and which coin is used first, then show the code.
- Scan the shop’s code (where a PayPay QR code is on display): tap any Scan icon in the Binance app, scan the shop’s PayPay QR code, check (or enter, if asked) the yen amount, the USDT to be taken and the rate, then tap Pay.
- When the success page appears, show it to the cashier if they ask.
Fees and limits. Binance says there is no transaction fee and no gas, but turning crypto into yen goes through an exchange rate, which the confirmation page shows live before you pay; that rate is what tells you what the purchase really cost. The limit is 12,600 USD (about 2,000,000 yen) per payment. Showing your payment code needs no extra verification up to 450 USD (about 70,000 yen); scan-to-pay generally asks you to verify each payment, and small password-free payments can be switched on under Settings, Payment Settings, Password-Free Payment. At launch Binance also ran a limited-time 10% instant discount; the announcement gives no end date or cap, so check the app before counting on it.
Which PayPay shops won’t take it
A PayPay sign at the door is not a guarantee. Binance lists these as unsupported:
- online shops (this covers in-person shops only);
- some taxis and vending machines;
- merchants that need Japanese identity checks, such as those selling tickets, securities, funds, virtual currency or insurance, or collecting rent;
- shops with a "PayPayマネー" (PayPay Money only) sign;
- some barcode-payment merchants, and PayPay merchants that don’t support cross-border payments.
If you’re turned down, pay with cash or a card instead. Carrying some yen or a card that works in Japan as a backup is a suggestion, not a Binance requirement.
Payment failed, order expired, charged wrongly or want a refund
- "Order Expired" pops up: that payment was cancelled and refunded automatically. Tap Show Payment Code again and ask the cashier to scan within 3 minutes.
- It says the payment failed but money left your account: Binance says such payments are generally cancelled and refunded to your Binance account; the refund details are in your Binance Pay transaction history.
- Charged twice or the wrong amount: go to the shop first. If that doesn’t work, or you’ve already left Japan, contact Binance support within 60 days of the payment with supporting documents such as the receipt.
- You want a refund: you can’t cancel a completed payment yourself; refunds are the shop’s decision, so ask the shop. "The refund is processing" only means the shop is working on it, and you get a notification once it lands. The amount back may differ from what you paid, because payment and refund are converted separately at each day’s rate; Binance says no handling fee is charged.
You are still spending the coins in your account. If you’d have to buy USDT first, the buy-price gap and deposit fee covered above still apply; and whether paying with crypto is allowed where you live, and whether it needs declaring, is the same question as in the compliance note earlier.
A tickable list before you register and use it
Before you send any USDT, tick through this list. If any line won't tick, stop there and clear it up; don't push on carrying a question mark.
- I reached the exchange through a trusted entry point, not a link from a private message, an ad or an unknown source.
- I confirmed whether my region is within the platform's supported range.
- I know the three costs on this route (buy fee, network fee, top-up fee) and have added them up on the amount I plan to send.
- The merchant or service I'm paying is one that clearly accepts Binance Pay or crypto itself, not something a middleman relayed to me.
- I know a crypto transfer is basically irreversible once sent, with no bank-style chargeback.
- I have a clear sense of my region's crypto-related rules and tax expectations, or have already looked them up.
- I plan to run the smallest amount through first to confirm the whole line works, before considering a normal amount.
- No one in the process has asked me for a password, verification code, private key or seed phrase; if anyone does, I stop at once.
Where you most often lose money or get scammed
Losing money on this route is rarely about "the market"; it's usually falling into a few fixed traps. The decode card below takes apart the most common live script you'll hear; a few equally frequent ones follow.
Someone messages you"My USDT price is better. Add me and transfer directly, cheaper than the exchange."
Beyond that one, a few stages are just as common, by how often they show up:
- Landing on a fake or phishing site. A link from a private message, a group chat or an ad leads to a page that looks almost identical. Money topped up there goes straight to a scammer. The fix: don't follow links strangers send you; sign up and log in through a trusted entry point.
- Sending coins to the wrong network or address. USDT runs on several networks (chains); the wrong network or one wrong character and the coins can be gone for good. The trial-run habit below is what catches this before it costs you the full amount.
- Paying a fake merchant. A page dressed up as "top-up on your behalf" takes your USDT and disappears. Only pay parties you've verified whose official side clearly accepts crypto.
- Falling for "pay to unlock first". Anyone asking you to "pay a deposit, unlock fee or processing fee before you can continue" is almost always running a scam; see the next section.
When you must stop immediately
An on-chain transfer has no undo button, so the judgement has to happen before you press confirm. If any one of these lands, don't take that step:
One: someone tells you to "pay an unlock fee, deposit or processing fee first before you can withdraw or continue". This is the core face of the scam. Legitimate payment and withdrawal have no "hand over money first to be released" logic. However neatly the reason is dressed up, it is a scam. Stop and pay nothing more.
Two: someone claiming to be support asks you for a password, verification code, private key or seed phrase, saying they'll "operate it for you". That information is the key to your account and assets, and no legitimate platform will ask for it. Anyone who does is trying to take your money. This site will never collect it either.
Three: the other side keeps pushing you to "transfer quickly, the chance is about to disappear" and won't give you time to check. Manufactured urgency is standard scam kit. The harder they push, the more you should stop and work out who the counterparty is. A missed "chance" is no loss; money sent to the wrong place is what you can't get back.
Send an amount small enough not to hurt, and finish the flow
Don't jump in at the amount you actually need to pay. First run the whole line with a sum so small that losing it wouldn't sting, confirm every step does what you expect, then scale up.
- Check first, register second. Confirm your region is supported, sign up through a trusted entry point, then finish identity verification.
- Buy the smallest amount of USDT. Buy a tiny bit at the platform's minimum, watch the fee it shows, compare it against the official page, and get a feel for the number.
- Do one small "spend". Via Binance Pay, pay a tiny amount to a merchant you've confirmed accepts it; via a virtual card, top up a little and confirm the balance credits and the card swipes.
- Check the result, then decide whether to scale up. Only once it credited correctly, the fee is within what you'll accept, and nothing jammed should you consider a normal amount. If anything goes sideways, stop and clear it up; don't add money carrying a question.
Run that smallest amount once and you'll get a concrete feel for how it works, what each step deducts, and how fast it is, more useful than ten how-tos. Put this run's fees next to the route where your card kept getting declined, and "does it really save, is it worth it" answers itself. Treat that first tiny send as the dress rehearsal: it proves the whole path works before any sum you'd mind losing rides on it.
A few questions people ask
- Is paying with USDT always cheaper than a card?
- Not necessarily. What it saves is the "card declined" hassle, which isn't the same as a lower cost. On Binance on 28 September 2026 buying cost 0.1% and withdrawing 0.01 to 1.5 USDT depending on network, before any top-up fee at the other end. Whether it saves money is a sum against your old method, and on small amounts it rarely does.
- Does USDT swing up and down like other crypto?
- It is designed to track one US dollar, so the aim is relative steadiness, mainly for moving money and paying, not for chasing a price gap. But "designed to be stable" is not the same as zero risk; it depends on the issuer's ability to back it, so don't treat it as an absolute safe box, and never expect a return by using it as an investment.
- If I send a transfer to the wrong place, can I get it back?
- Basically not. A crypto transfer has no bank-style reverse or chargeback; once it's sent, it's gone. That is exactly why the first send should be a throwaway-sized trial: you verify the network and address on a sum you could shrug off losing, and only then move the real amount.
- Is this actually legal where I am?
- Only you can judge that by your local law. Rules on holding, buying, selling and using crypto assets differ a great deal by place, and some involve declaring and tax. This site makes no compliance call for any country; if you're unsure, look it up and ask first, then decide.
- Can residents of Japan pay at PayPay with Binance Pay?
- No. Binance says the feature is open only to tourists physically in Japan on a Japanese IP who have completed identity verification and use the latest Binance app, and it is not available to residents of Japan. A visitor who qualifies can show a payment code or scan the shop’s QR code at in-person PayPay merchants, and the coins are converted to yen automatically.
Checked on 2026-09-28: Binance's spot fee schedule, its public list of withdrawal networks and fees, and its help page on self-service recovery; on 2026-10-13, Binance’s announcement and help page on paying at PayPay merchants in Japan. Whether you may do this at all is a question of the law where you live. This guide explains the flow and the risks; it isn't investment, tax or legal advice. Updated 2026-10-13.
References
- Binance: official fee schedule (spot trading)
- Binance Support: retrieve a deposit that hasn't arrived with self-service recovery
- Binance announcement: Binance Pay at PayPay merchants for tourists in Japan (2026-09-30)
- Binance Support: how visitors pay with Binance Pay at a PayPay merchant in Japan
The first two are Binance's fee page and its recovery help page; the last two are its announcement and help page on paying at PayPay in Japan. On-chain network fees fall outside the fee page and move with congestion, so there is no fixed figure worth quoting.